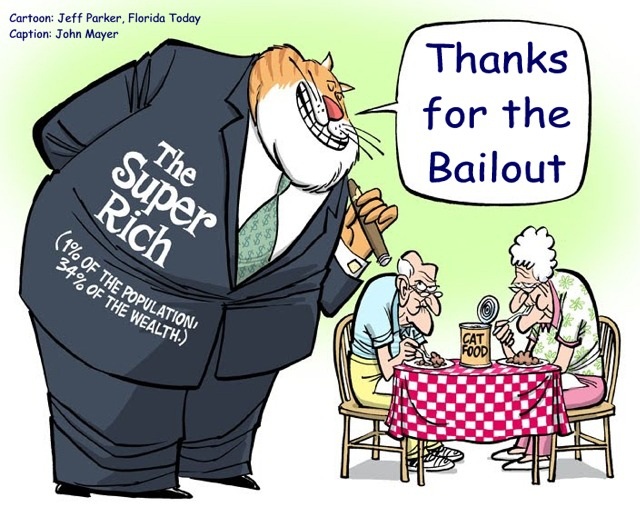
"Our Children and Grandchildren are not merely statistics towards which we can be indifferent" JFK
Showing posts with label Stock Market. Show all posts

Friday, August 5, 2011

Why the Market Gods are Angry (Dylan Ratigan)

"We have a broken financial system, and capitalism
has been broken in this country for some time,"


Huffington Post
By Dylan Ratigan
August 4, 2011

For nine of the last ten days, the Dow has been dropping, concluding with a 500 point drop, our biggest sell-off in two years.

What happened?

A combination of bad economic data from Europe and the US validated the market fears that Western governments lack the integrity to solve problems and meet global economic challenges.

We are witnessing well-informed investors conclude future employment and production in the West is in jeopardy as a result of the governments' apparent inability to solve problems. They are seeking to reduce their exposure to the future production of Western countries because it does not appear that these governments can deal with expectations of sustained unemployment and diminished prosperity in a way that is constructive.

"We have a broken financial system, and capitalism has been broken in this country for some time," said Seattle-based hedge fund investor Bill Fleckenstein. "Folks need to take a step back and realize that this reaction that happened today was not a reaction to the debt ceiling. We've done that dance many times before."

Data released on Monday showed that manufacturing activity in the US economy is rapidly dropping. Today Italian bonds blew up on a risk the Italian government won't be able to pay its debts. Tomorrow the assumption is that there will be yet another tepid jobs report.

And yet, the US Congress is engaged in an absurd battle about whether air traffic controllers should be paid and our president is planning a fundraising bus tour for his birthday (By the way, happy birthday Mr. President).

Is it any wonder that global investors are skeptical of American prospects for employment and prosperity? Some people ask, why today? It's not like these problems are new. I think of it as water being heated up. It's water until it hits 212 degrees, at which point it turns to steam.

Any other country in this situation would be in trouble. However, because we print the dollar, which is the global standard (or "reserve currency"), we get a stay of execution. It's why despite all of this, our government can still borrow money cheaply. This ability to borrow is a blessing and a curse. It's a blessing because it prevents a more precipitous exit from America and buys us time to fix our problems. It's a curse because it enables us to continue on this reckless path.

Let's hope that this relative market pinprick got someone's attention at the White House, or on the tour bus. Because the market's tendency is to ratchet up the pain for those who fail to recognize its message.

"Over here, [Federal Reserve Chairman] Ben Bernanke stopped QE2 and has convinced people that he has their back. Now, they've got a gun to his head and the markets are saying 'give us more QE3 or we'll melt the markets down by Wednesday. The markets are going to force the politicians to deal with these problems... we have to admit these things and solve these things."

Saturday, April 9, 2011

Comstock Partners: investors are in a state of denial, ignoring all of the bad news that is certainly no secret, Looks like 2000/2007 Part Deux

The spread between the percentage bullish
and the percentage bearish soared to 41.6,
the widest since October 2007,
when the market peaked.

Comstock Partners, Inc.
April 7, 2011

In both late 1999 and 2007 we warned against the mentality that caused investors to overlook the dire-looking events that were swirling all around them. The warnings were generally ignored on the grounds that you couldn't fight against a market that was continually rising. Of course, we now know the eventual outcome. Once again the market is rising despite a spate of negative factors that are widely known to the investing public. The main bullish theme is that the economic numbers are improving, corporate earnings are robust and the Fed will guarantee this will continue even if it has to institute QE3 and QE4. Unfortunately, however, a number of factors are indicating that the good fortune is about to end soon. We cite the following.
  1. QE2 is ending on June 30th. The program will, by that time, have pumped $600 billion into the economy, meeting Chairman Bernanke's stated goal of jump-starting the stock market. The end of the program means a defacto tightening of monetary policy. This has been the major factor holding up both the stock market and a fragile economy that will not be self-sustaining once the Treasury bond purchases are halted. A continuation of quantitative easing is highly unlikely as it would be politically difficult. Furthermore an increasing number of FOMC members are themselves hinting at a possible imminent tightening.
  2. Fiscal policy is about to tighten as well. That is obviously what the discussion in Washington is all about. Whether the government temporarily shuts down or not is a non-issue. The fact is that, one way or another, both sides of the debate are now intent on reducing the federal deficit. So, whatever the merits, both fiscal and monetary policy will be less easy. That is a headwind against the economy and stock market
  3. A broad array of commodity prices is rising. This is increasing corporate costs at a time when they will be difficult to pass on as consumers are strapped for income and are paying down debt. This is bound to squeeze profit margins in the period ahead and result in downward earnings guidance.
  4. The Mid-East turmoil is continuing and showing no signs of slowing down. Although the eventual outcome is unknown, it is doubtful that it will be market-friendly.
  5. The European Union (EU) is another major problem. First the authorities tried to build a firewall around Greece, second around Ireland, and now around Portugal. These are relatively small economies, and the EU can probably "kick the can down the road" one more time with no real solution in sight. Now they are attempting to build a wall protecting Spain, a nation said to be "too big to fail and too big to rescue". If Spain follows the lead of Greece, Ireland and Portugal, the results could be catastrophic to the global financial system. In the midst of these events the EU has also raised interest rates, a move they last made in the summer of 2008 just prior to the credit crisis.
  6. China is battling against soaring inflation and has increased interest rates four times in the last five months in an attempt to slow down the economy. No financial bubble has ever been stopped without a recession, and we doubt that this will be the first. This would have major ramifications on the global economy including the commodities markets, emerging market suppliers, multinational corporations and the U.S bond market.
  7. The Japanese earthquake is yet another headwind to the economy. Toyota is shutting down all of its American factories, and American vehicle manufactures are facing parts shortages as well. According to AutoNation, "production disruptions will significantly impact product availability from Japanese auto manufacturers in the second and third quarters." We're hearing about supply disruptions in a number of other industries as well. We won't be surprised to hear numerous companies comment on this issue when they report first quarter earnings and give guidance for the rest of the year.
All in all, we see the tailwinds that have helped the economy and markets over the past year suddenly turning into headwinds. We expect to see downward revisions in both economic growth and corporate earnings in the period ahead. At the same time, according to "Investors' Intelligence" , the bears seem to have thrown in the towel as the percentage of bears dropped to 15.7%, the lowest since December 1999. The spread between the percentage bullish and the percentage bearish soared to 41.6, the widest since October 2007, when the market peaked. Just as in early 2000 and late 2007, investors are in a state of denial, ignoring all of the bad news that is certainly no secret. Comstock Partners Bios


Sunday, March 27, 2011

Stock Market in Denial (Comstock Partners)

In sum investors are in a state of denial
similar to when they denied the dot-com boom
was a serious problem in early 2000,
or that subprime mortgages
were a problem in 2007

Hope is the denial of reality.
Margaret Weis


Comstock Partners
March 24, 2011

Those of you who watch financial TV or read the financial media have probably heard the current market referred to as the "nothing matters" market since it is supposedly ignoring a spate of negative news. According to this view, the negative news is exogenous and temporary while the true backbone of the market is the so-called strengthening recovery that has a long way to go. We have a number of disagreements with this point of view.

First, you may have noticed that the market has not exactly ignored the problems. The S and P 500 peaked about five weeks ago at 1344 and then proceeded to fall 7.1%. It has since climbed back by 4.6% in a rally that looks somewhat anemic by past standards. This type of action is actually typical of the way most bear markets begin. Generally bear markets go through three psychological phases----denial, concern and capitulation. Most often, but not always, the market rallies between each phase. The denial phase is the initial downleg from the bull market high, and we are only at the start of that downleg now.

During the denial phase the majority of investors are still in a bullish frame of mind after seeing continual profits in their account and having seen the market bounce back from prior corrections. They look upon the decline as merely another buying opportunity and think that stocks are cheap. In addition the fundamentals during this period are still perceived as positive and any negative news is downplayed.

Second, we don't regard the negative news as necessarily temporary, and only the tragic Japanese earthquake is truly exogenous. The European sovereign debt problem is a spillover from the massive 2008 credit crisis, and is not going to be resolved anytime soon. When the crisis initially emerged in Greece it was reasonably clear that the problems could spread to Ireland, Portugal and Spain, and, so far, has continued along that path. The Mid-East, North African crisis was always of a matter of "when" rather than "if" and was a recognized risk. It is not going away soon. China is engaged in the high-wire act of attempting to rein in inflation without causing a recession, a feat that historically has had a low chance of success.

It is also far too early to dismiss the Japanese earthquake as a passing phenomenon.  We still don't know how this will all play out.  With high levels of radiation in the water and farmland of the affected area, we don't know if this will become a "dead zone" for years to come. We have also heard about the possibility of significant global supply disruptions and reduced output that could presage lower demand and scarcities.

Third, the so-called strengthening recovery that supposedly more than offsets all of the above is highly fragile and subject to reversal. The second dip in housing that we have expected is now upon us. House prices are falling and inventories are extremely high while close to a quarter of homes with mortgages are underwater. The further dip in prices will put even more mortgages underwater, leading to even more foreclosures and an undermining of consumer net worth, confidence and spending. Real wages have decreased in four of the last five months and even new orders for durable goods, a precursor for capex, has weakened in the last two months.

In addition let's not overlook the point that QE2, which is pouring about $3.5 billion into the economy every weekday, is due to end on June 30th, and is unlikely to be extended. Both the economy and the market slowed significantly after the conclusion of QE1 and came back only with the announcement of QE2. At that point monetary policy becomes a headwind instead of tailwind at a time when political pressures are reining in fiscal policy as well.

In sum investors are in a state of denial similar to when they denied the dot-com boom was a serious problem in early 2000, or that subprime mortgages were a problem in 2007. This is typical of investor behavior at tops in all publically traded markets over hundreds of years, and human behavior is not likely to suddenly change now.

Tuesday, March 8, 2011

Stocks react to a made up number (Herb Greenberg) and guidance is a myth

The quarter guidance game is a myth

CNBC Stock Blog
By Herb Greenberg
March 8, 2011

Shocker: Contrary to what you probably believe — at least contrary to my belief! — most companies do not give quarterly earnings guidance.

According to Factset, which did a run at my request:
  • Only 96 of the S&P 500 give quarterly earnings guidance.
  • 64 offer sales guidance.
  • 50 give both quarterly sales and earnings guidance.
The story is much different with annual guidance, reflecting a growing trend of recent years, as companies have tried to pry themselves from such short-term orientation.

Further, according to Factset:
  • A more robust 225 give annual earnings guidance.
  • 144 give annual sales guidance.
  • 116 give both annual sales and earnings guidance.
The grand finale: Only 30 give quarterly and annual earnings and sales guidance.

Moral of the story: The quarter guidance game is a myth. All of that fuss about missing, meeting and beating every quarter is mostly the result of analysts conjuring up their own numbers, resulting in a consensus that the companies than either miss, meet or beat.

Which means, in the end, stocks react to a made-up number.

Absurdity, squared.

Read More Herb Posts

Saturday, February 19, 2011

Bill Fleckenstein: The Bulls will be punished before the year's out (King World News)

Link to interview with Bill Fleckensten
(click play when site boots...telephone interview)


Interview Recap via Business Insider
By Mamta Badkar
February 18, 2011

Bill Fleckenstein is still giving loud warnings about a QE-induced stock bubble.

He tells King World News investors are getting drunk at the punchbowl:

What's happened with money printing this time around is people have gotten a little financially drunk again.

Fleckenstein says the bubble is becoming obvious in tech stocks -- which surprises him given what we've been through:

We're working on you know internet badness 2.0 now, with social networking and all the other stuff, Facebook, Groupon and all this other stuff. There's a lot of speculation in tech stocks now and so there's a lot of things that you wouldn't think would be occurring now given what we've been through, and given the economic backdrop, but that's what money printing does.

Fleckenstein says the bulls will be "punished" before the year's out:
"Trying to guess how high is high and how long it can last is really impossible, and people that try to pick a top will probably lose a bunch of money."

Additional Insight from Bill Fleckenstein
Link to articles by Bill Fleckenstein in MSN Money. Video with Bill Fleckenstein and Dylan Ratigan

Do We Think We Are Better Off Than Our Parents? Only if your parents were named Wall and Street.


By Annalyn Censky
Staff reporter


NEW YORK (CNN Money) -- Are you better off than your parents?

Probably not if you're in the middle class.
Incomes for 90% of Americans have been stuck in neutral, and it's not just because of the Great Recession. Middle-class incomes have been stagnant for at least a generation, while the wealthiest tier has surged ahead at lighting speed.

In 1988, the income of an average American taxpayer was $33,400, adjusted for inflation. Fast forward 20 years, and not much had changed: The average income was still just $33,000 in 2008, according to IRS data.

Meanwhile, the richest 1% of Americans -- those making $380,000 or more -- have seen their incomes grow 33% over the last 20 years, leaving average Americans in the dust.


Experts point to some of the usual suspects -- like technology and globalization -- to explain the widening gap between the haves and have-nots.

But there's more to the story.

A real drag on the middle class
One major pull on the working man was the decline of unions and other labor protections, said Bill Rodgers, a former chief economist for the Labor Department, now a professor at Rutgers University.

Because of deals struck through collective bargaining, union workers have traditionally earned 15% to 20% more than their non-union counterparts, Rodgers said. But union membership has declined rapidly over the past 30 years. In 1983, union workers made up about 20% of the workforce. In 2010, they represented less than 12%. "The erosion of collective bargaining is a key factor to explain why low-wage workers and middle income workers have seen their wages not stay up with inflation," Rodgers said. Without collective bargaining pushing up wages, especially for blue-collar work -- average incomes have stagnated.

International competition is another factor. While globalization has lifted millions out of poverty in developing nations, it hasn't exactly been a win for middle class workers in the U.S. Factory workers have seen many of their jobs shipped to other countries where labor is cheaper, putting more downward pressure on American wages. "As we became more connected to China, that poses the question of whether our wages are being set in Beijing," Rodgers said.


Finding it harder to compete with cheaper manufacturing costs abroad, the U.S. has emerged as primarily a services-producing economy. That trend has created a cultural shift in the job skills American employers are looking for. Whereas 50 years earlier, there were plenty of blue collar opportunities for workers who had only high school diploma, now employers seek "soft skills" that are typically honed in college, Rodgers said.

A boon for the rich
While average folks were losing ground in the economy, the wealthiest were capitalizing on some of those same factors, and driving an even bigger wedge between themselves and the rest of America.

For example, though globalization has been a drag on labor, it's been a major win for corporations who've used new global channels to reduce costs and boost profits. In addition, new markets around the world have created even greater demand for their products.

"With a global economy, people who have extraordinary skills... whether they be in financial services, technology, entertainment or media, have a bigger place to play and be rewarded from," said Alan Johnson, a Wall Street compensation consultant.

As a result, the disparity between the wages for college educated workers versus high school grads has widened significantly since the 1980s. In 1980, workers with a high school diploma earned about 71% of what college-educated workers made. In 2010, that number fell to 55%.

Another driver of the rich: The stock market.
The S and P 500 has gained more than 1,300% since 1970. While that's helped the American economy grow, the benefits have been disproportionately reaped by the wealthy. And public policy of the past few decades has only encouraged the trend. The 1980s was a period of anti-regulation, presided over by President Reagan, who loosened rules governing banks and thrifts. A major game changer came during the Clinton era, when barriers between commercial and investment banks, enacted during the post-Depression era, were removed.

In 2000, President Bush also weakened the government's oversight of complex securities, allowing financial innovations to take off, creating unprecedented amounts of wealth both for the overall economy, and for those directly involved in the financial sector. Tax cuts enacted during the Bush administration and extended under Obama were also a major windfall for the nation's richest.

And as then-Federal Reserve chairman Alan Greenspan brought interest rates down to new lows during the decade, the housing market experienced explosive growth. "We were all drinking the Kool-aid, Greenspan was tending bar, Bernanke and the academic establishment were supplying the liquor," Deutsche Bank managing director Ajay Kapur wrote in a research report in 2009.

But the story didn't end well. Eventually, it all came crashing down, resulting in the worst economic slump since the Great Depression.  With the unemployment rate still excessively high and the real estate market showing few signs of rebounding, the American middle class is still reeling from the effects of the Great Recession.

Meanwhile, as corporate profits come roaring back and the stock market charges ahead, the wealthiest people continue to eclipse their middle-class counterparts. "I think it's a terrible dilemma, because what we're obviously heading toward is some kind of class warfare," Johnson said.


Friday, February 18, 2011

Stock Market is Increasingly Irrelevant (Felix Salmon)

Seeking Alpha
By Felix Salmon
February 14, 2011

I’m sad that my NYT op-ed on the decline of stock exchanges went to press too late to include the bonkers rhetoric emanating from Chuck Schumer:

The New York Stock Exchange is the cradle of American capitalism. It is a national treasure. In America, we start each day in our Congress and in our classrooms with the Pledge of Allegiance, and we also start it with the ringing of the bell on the floor of the stock exchange.

The NYSE is in no sense the cradle of anything. A cradle is a safe place for the young to develop until they grow up and become more self-sufficient. Y Combinator is a cradle. The NYSE is place for algorithms and speculators to make bets on financial assets. It last funneled real amounts of money into the broader economy during the dot-com boom, leaving behind a lot of Aeron chairs and little else. Since then, I get the feeling that the big capital raises on U.S. exchanges have been by financial institutions, rather than the real economy; maybe someone can find a breakdown for me of which sectors raised the most money in primary and secondary offerings over the past ten years.

As for the idea that the NYSE is a national treasure akin to the Pledge of Allegiance, well, yes. Which is to say, its value is symbolic, and rooted in the days of old, when “allegiance” meant something more than who you’re friends with on Facebook, and when institutions were judged on the size and weight of their Corinthian columns.

There’s one other point I would have liked to make in my piece, which is that the tax code is a large part of the reason why the stock market is bad at capital formation. Look at the trillions of dollars cash on corporate balance sheets: why aren’t those companies paying it out as dividends to their shareholders? In an efficient capital market, they would do just that, and then raise new equity capital as and when they needed it in future. After all, sitting on billions of dollars in cash is hardly a core competency of most exchange-listed corporations.

But companies don’t do that. It’s partly because they fear that the money might not be there when they need it. But it’s also because the cost to shareholders of dividending out money now and then getting it back again in future is enormous. For one thing, the underwriters of the secondary offering are likely to require a hefty seven-figure fee when you ask them to raise that money for you. And more importantly than that, the shareholders you send the dividend to are going to have to pay income tax on it, at rates in the region of 35% to 40%. There’s no way that can be efficient.

I’m not saying that we should abolish the income tax on dividends. But it does help to explain why U.S. capitalism can be very inefficient, and why the stock market, broadly speaking isn’t working very well these days when it comes to its core function of capital allocation.

More Articles by Felix Salmon

Sunday, February 13, 2011

The stock market is overbought and is losing momentum (this is not a test)

In summary, the current excitement about
the market reminds us of the
extreme bullishness exhibited near the
tops in early 2000 and late 2007.
The outcome is likely to be the same.

Comstock Partners
February 3, 2011
The stock market is at a highly vulnerable point, both fundamentally and technically. Fundamentally, the current rate of economic growth is unsustainable and the valuation of the S and P 500 is significantly above its long-term average. Technically, the market is overbought and is losing momentum. We cite the following points.
  • Consumer spending has been outpacing the ability to spend. Spending has exceeded income in five of the last six months. During this time nominal spending has increased 2.8%, compared to only 1.9% in personal income. In order to accomplish this, households took their savings rate down to 5.3% of income from 6.3% six months earlier. As we have pointed out numerous times, household debt is still near record levels and consumers still have a long way to go in deleveraging their balance sheets.
  • Housing remains a major weak spot with a rising pipeline of coming foreclosures, excess inventories and falling prices. In addition rising bond rates are causing mortgage rates to climb. (UPDATE: 30 year mortgage rate jumped to 5.05% this past week from 4.81% prior week)
  • States and local governments are slashing budgets through a combination of raising taxes and cutting spending. This, obviously, is a major drag on the overall economy.
  • Private jobs have increased at an average of 112,000 a month over the past year, but about half of that has been in low-paying health care, social services and temporary employment. (UPDATE: on 2/4/11, BLS reported a net +36,000 jobs in January)
  • QE2 is scheduled to end in five months. Just as the anticipation of QE2 in August led to a substantial rise in the market, the anticipation of its ending may well have the opposite effect, combined with the other factors we mention.
  • With commodity prices soaring and consumers unable or unwilling to accept price increases, a large number of corporations will undergo major cost increases that will squeeze profit margins, a factor not calculated into current earnings forecasts. (UPDATE: Kraft Foods states revenue growth will be from higher prices versus higher volume)
  • Europe's sovereign debt problems have not been solved and the crisis will continue to fester. Any real solution will not be friendly to economic growth.
  • The crisis in Tunisia and Egypt are not random exogenous events. Soaring food prices, high unemployment and wealth disparities are as much a factor as repressive governments. People tend to tolerate dictatorships more when they aren't hungry.
  • China is a bubble waiting to burst. Think back to the late 80's when everyone was as optimistic about Japan as they are about China today.
  • At today's closing price the S and P 500 is selling at 19.2 times cyclically smoothed reported earnings, compared to a historical average of about 15. (UPDATE: the S and P 500 is up another 34 points/2.7% as of the close on 2/11/11)
  • In addition to the above fundamentals the market is technically vulnerable. It has climbed about 95% over the last 23 months and 30% since the July low. Sentiment has become heavily bullish while the market is losing momentum as fewer stocks are moving higher on each successive top. Volume for advancing stocks is dropping while volume for declining stocks is rising. The number of new daily highs is also dropping as is the percentage of stocks making new 50-day highs.
In sum, the current excitement about the market reminds us of the extreme bullishness exhibited near the tops in early 2000 and late 2007. The outcome is likely to be the same. Add'l Posts/Articles by Comstock Partners

Tuesday, January 25, 2011

Merrill (Bank of America) Pays $10 mil to hop over the Chinese Wall

Remember the Chinese Wall, you know, the wall that separates Wall Street proprietary traders and those placing client orders. Like when you call your financial advisor to place a trade assuming it is between you and the advisor. Yeah right! Oh your order was filled, however you paid more than you had to because the information was shared with the proprietary traders so they could buy ahead of you, make a few pennies and sell you their shares at a higher cost.

Remember though, these are the fine folks that received a TARP bailout in order to prevent financial armageddon and it was good for we Main Street folk. When they get caught with their hand in the cokkie jar, just write out a check and admit to NOTHING!

By Jonathan Stempel
1/25/2011

(Reuters) - Bank of America Corp's Merrill Lynch unit agreed to pay $10 million to settle U.S. Securities and Exchange Commission charges that it fraudulently misused customer orders so it could trade for its own benefit.

The settlement stemmed from SEC charges that Merrill used the order information to place proprietary trades on a desk it no longer operates. The SEC also accused Merrill of charging hidden trading fees to institutional and wealthy customers.

Merrill did not admit wrongdoing in agreeing to settle.

"It's a slap on the wrist," said David Robbins, a partner at the law firm Kaufmann, Gildin, Robbins & Oppenheim LLP in New York and a former compliance chief at the American Stock Exchange. "This penalty is like a traffic ticket. If the desk had still been around, you can be sure the sanction would have been to close it down."

According to the SEC, from February 2003 to February 2005 Merrill operated a proprietary trading desk on its equity trading floor in New York known as the Equity Strategy Desk.

It said that while Merrill told customers their orders would generally be kept private, traders on the Equity Strategy Desk would learn information about orders from institutional clients and use it to place trades with Merrill's own money.

"Investors have the right to expect that their brokers won't misuse their order information," Scott Friestad, associate director in the SEC enforcement unit, said in a statement. "The conduct here was clearly inappropriate."

The SEC also found that from 2002 to 2007, Merrill charged undisclosed fees to some institutional and high-net-worth customers when filling orders for "riskless principal trades."

Such trades occur when a broker-dealer receives a customer order, conducts a contemporaneous offsetting trade, and then "allocates" the securities to the customer, the SEC said.

Bill Halldin, a Bank of America spokesman, said in a statement that Merrill has adopted "a number of policy changes" to separate proprietary trading from other trading, and has improved training and supervision related to principal trades.

The SEC said the $10 million penalty took into account remedies taken by Merrill after Charlotte, North Carolina-based Bank of America acquired the company at the beginning of 2009. Bank of America is the largest U.S. bank by assets.

"The fact Merrill didn't self-regulate is the bigger problem," Robbins said. "I hope other firms will see this as a signal to stop trading on confidential customer information."


Wednesday, January 12, 2011

$4.2 billion withdrawn from U.S. Equity Funds 1st week of 2011

Since the end of April 2010, over $93 billion has been withdrawn from U.S. Equity funds. During this time frame, ONE week was a net inflow. The U.S. stock market has been and continues to be a complete farce. The charts below say it all, AS MORE MONEY IS WITHDRAWN FROM THE MARKET, THE HIGHER THE MARKET MOVES.

Washington, DC, January 12, 2011 - Total estimated outflows from long-term mutual funds were $717 million for the week ended Wednesday, January 5, the Investment Company Institute reported today. Flow estimates are derived from data collected covering more than 95 percent of industry assets and are adjusted to represent industry totals.


Equity funds had estimated outflows of $1.81 billion for the week, compared to estimated inflows of $2.74 billion in the previous week. Domestic equity funds had estimated outflows of $4.23 billion, while estimated inflows to foreign equity funds were $2.42 billion. Complete report

Total Domestic Equity Flows/Week Ending
-$4.229 billion 1/5/11
+$456 million 12/29/10
-$453 million 12/21/10
-$2.401 billion 12/15/10
-$2.631 billion 12/8/10
-$1.746 billion 12/1/10
-$2.606 billion 11/23/10
-$2.805 billion 11/17/10
-$660 million 11/10/10
-$1.132 billion 11/3/10
-$6.788 Billion for the month of October 2010
-$14.387 Billion for the month of September 2010
-$15.696 Billion for the month of August 2010
-$11.250 Billion for the month of July 2010
-$7.708 Billion for the month of June 2010
-$19.229 Billion for the month of May 2010

Since April 30th, 2010, $93.265 BILLION has been withdrawn from Domestic Equity Funds


Thanks to Zero Hedge for the copy and paste charts


NYSE Rule 48 (to assure an orderly manipulation of the stock market)

By Matt Phillips
May 20, 2010

If you’re interested. Here’s the text of “Rule 48,” which the NYSE invoked to smooth the open today. Here’s the Cliffs Notes version:

(a) In the event that extremely high market volatility is likely to have a Floor-wide impact on the ability of [Designated Market Makers] to arrange for the fair and orderly opening, reopening following a market-wide halt of trading at the Exchange, or closing of trading at the Exchange and that absent relief, the operation of the Exchange is likely to be impaired, a qualified Exchange officer may declare an extreme market volatility condition with respect to trading on or through the facilities of the Exchange.

(b) In the event that an extreme market volatility condition is declared with respect to trading on or through the facilities of the Exchange, a qualified Exchange officer shall be empowered to temporarily suspend at the opening of trading or reopening of trading following a market-wide trading halt: (i) the need for prior Floor Official or prior NYSE Floor operations approval to open or reopen a security at the Exchange (Rules 123D(1) and 79A.30); and/or (ii) applicable requirements to make pre-opening indications in a security (Rules 15 and 123D(1)).

Dow Jones’ Kristina Peterson explained it pretty well in a story earlier this month. She writes that basically it means the designated market makers “will not have to disseminate price indications before the bell, making it easier and faster to open stocks. The rule was approved by the Securities and Exchange Commission on Dec. 6, 2007 and has been used rarely since then.”


Tuesday, January 11, 2011

Surest way to profit from takeover speculation in the stock market is to bet it’s wrong.

Deliberately spreading false rumors may
violate securities laws, especially if
the intent is to sway prices
(appears the SEC quietly endorses rumors if stock
price moves higher, however don't you dare
start a rumor that sends a stock lower...)


By Tara Lachapelle
Jan. 11 (Bloomberg) -- The surest way to profit from takeover speculation in the stock market is to bet it’s wrong.

Electronic news services, brokerages and newspapers reported at least 1,875 rumors about potential buyouts of 717 companies between 2005 and 2010, according to data compiled by Bloomberg. A total of 104, or 14.5 percent, were acquired, the data show. While stocks that were the subject of takeover speculation initially jumped 2.9 percent, betting on declines yielded average profits of 1.2 percent in the next month, an annualized gain of 14 percent.

Opportunities to employ the strategy are increasing as mergers recover from the worst recession in more than 70 years, data compiled by Bloomberg show. After bottoming in 2008, the number of unconfirmed stories about possible mergers surged 71 percent to 611 last year from 2009, data compiled by Bloomberg from more than 50 news providers and brokerages show.

“Sell into the strength,” said John Orrico, who focuses on mergers and acquisitions at New York-based Water Island Capital LLC, which oversees about $2.2 billion. “We see it as an opportunity to sell if we think the rumor is false or ridiculous, which in most cases they are.”

Short selling to speculate on declines on supposed takeover targets produced more than twice the average return generated by U.S. stocks, data compiled by Bloomberg show. At the same time, companies in the Russell 3000 Index had the same chance of being acquired in any 12-month period since 2005 as those that were the subject of merger stories, the data show.

Versus S&P 500
Stocks tracked by Bloomberg fell 0.2 percent, 0.6 percent and 1.2 percent on average in the day, week and month following a rumor report, Bloomberg data show. The S&P 500 rose 0.03 percent, 0.2 percent and 0.5 percent on average during the same periods.

The 14 percent annualized profit from short selling compares with a 6.2 percent yearly return since 1900 before dividends for U.S. stocks, inflation-adjusted data from the London Business School and Credit Suisse Group AG in Zurich show. Short selling is the sale of borrowed stock in the hope of profiting by buying the securities later at a lower price and returning them to the shareholder.

Rumor Origination
“The question that remains unanswered is where does the takeover story originate,” said Michael McCarty, managing partner at Differential Research LLC in Austin, Texas. “It’s most likely from someone who’s interested in selling.”

Deliberately spreading false rumors may violate securities laws, especially if the intent is to sway prices, said James Cox, a professor at Duke University School of Law in Durham, North Carolina. Proving a market-manipulation case is difficult, according to Peter Henning, a law professor at Wayne State University in Detroit and a former federal prosecutor.

“You might be able to see a unicorn before you see a market manipulation case established based on rumors,” Henning said. “It’s so difficult to pin down, and even if you can, to try to link them. You get lots of investigations announced and very few cases brought.”

Manipulation 101
Netlist, Inc. a maker of computer-memory systems, rose 1.9 percent when rumors were reported on Dec. 28, 2009, that Microsoft Corp. might buy the Irvine, California-based company. The shares declined 2.2 percent a day later, 9.4 percent a week later and 31 percent in 30 days.  Complete article by Tara


Do you think the market cares about you? Well do ya punk?

But being as this is the U.S. stock market, the most manipulated
market in the world, and would would completely wipe you out,
you've got to ask yourself one question:
Do I feel lucky? Well, do ya, punk?


Pragmatic Capitalism
January 11, 2011
by Cullen Roche

Markets do not care about you. They don’t care about your family, your feelings and they particularly don’t care about your wallet. With record deficits, QE2, 9.4% unemployment, continuing stimulus and 0% interest rates many are still baffled by a surging stock market. What gives says the Main Street investor? Clearly, there’s still an enormous disconnect between the market and reality. I know, there are a lot of positive signs out there, but the fact remains – Main Street still doesn’t feel like the recovery is headed their way. But the market isn’t the economy. Main Street isn’t Wall Street. And the market is a heartless beast that desires one thing and one thing only- PROFITS!

Although we live in a world of the Bernanke Put and endless government bailouts the markets remain the last bastion of natural selection in the modern world. When allowed to truly function on its own capitalism is a cruel, heartless, but remarkably efficient bitch. The weak ultimately perish and the strong survive. For the strong the rewards are great. For the weak the losses are insufferable. And in this world of cruelty you must never forget that the system has no sympathy for you or your emotions.

The equity market is priced based on future profit expectations that are often right, but more often than not prove to be wrong. As we saw in 2007 those expectations were high, investors believed economic downturn would be thwarted and the environment ultimately surprised substantially to the downside. As the waterfall decline ensued we experienced the inverse reaction in 2009. Markets and expectations overshot to the downside. Expectations for profit growth became far too low and classic mean reversion ensued. As the economy stabilized in 2009 the economy remained stagnant at best. But the economy’s loss had become corporate America’s gain. The massive cost cuts made these corporations lean and mean. Corporate America’s diverse revenue stream kicked in as the global economy strengthened and leveraged up these lean balance sheets. Despite persistent weakness in the US economy profits continued to rebound through 2009 and 2010 even as US unemployment continued to climb. That heartless bitch did not care about the unemployed, stagnant wages or l-shaped recoveries. She cared only for the bottom line and the bottom line was robust – particularly when compared to expectations.

Over the years I have attempted to measure this disconnect between perception and reality using my Expectation Ratio. The metric was bearish since 2007 and was then bullish throughout the majority of the recent bull market. If I have made one mistake in recent years it has been focusing on what should be good for an economy (job growth, fair markets, organic growth, etc) as opposed to what the market desires (higher profits no matter how they come). But much like an approach to trading, your approach to conducting research must be unbiased, flexible and mechanical. Ultimately, the purpose of research is to generate investment profits. Connecting the dots between this research and actionable ideas is vital to success. If you allow the emotion of a macro outlook to infect your work your results will suffer. Remember, the market is not the economy. The market does not care about the emotions of the unemployed or the suffering. In fact, she feeds off the negative emotion and it is often not until you have become comfortable and complacent that she will turn her back on you and break your heart again.

As investors we are always learning, evolving and honing our skills in order to avoid the pitfalls that cause so many to self destruct. Few investment cycles have been as great a learning experience as this one. We live in a renaissance for economic thought, economic theory and investment. It’s unlikely that we will experience as many beneficial learning experiences as the most recent cycle. And while this environment continues to cause great pain there are also great lessons to be learned.

From an investment perspective, there has been no greater lesson than the fact that has been burned into my soul from the last 24 months – the market is not the economy and the market has no sympathy for you, your family or your emotions. She desires one thing and one thing only – profits. And those profits will often come at the expense of everything we wish for in this world. That’s the cruel reality of the capitalist system in which we reside. It might not be fair, it might not be right, but it is what it is. In the end, capitalism continues to be the most dynamic, innovative and productive system in the world. But make no mistake – that system does not care about you and anyone who forgets that will be devoured by it.

Pragmatic Capitalism was founded by Cullen Roche in the midst of the financial crisis of 2008. Mr. Roche foresaw many of the events that led up to the crisis and felt that the government was slow to react and when it did finally react, responded with the wrong medicine. While also providing relevant news and indicators the website remains very much a sounding board in which the various authors (and readers) can voice their opinions on markets, economics and public policy. In addition to regular commentary by Mr. Roche the website is a collaborative work from many different financial experts.


Wednesday, December 29, 2010

Brett Arends not a Believer of the Santa Rally (very good read)

If you need a breather from the odorous Bullpen, spend a few minutes reading Mr. Arends' perspective on the Santa Rally. Granted, the U.S. Stock Market deems fundamental data irrelevant. Ben Bernanke has Wall Street flush with cash in an effort to bid up all asset classes regardless of the outcome from yet another round of irrational exuberance.

Kind of eerie how similar the behavior of bullish pundits is to the tech wreck of the dot-bomb era, merely 10 years ago.

The Wall Street Journal
12/29/10

It's been quite a Santa Rally.

The stock market has gained about 10% this quarter. That's the best fourth-quarter performance since 2003 and the seventh-best in thirty years. Wall Street is cheering. The shops had a good Christmas. The economy may be perking up. Investors are feeling cheerful again, and strategists are predicting a happy new year for equities.

Two words: Bah, humbug.

I can't cheer this Santa Rally. Call me Scrooge. But I'll give you ten reasons why not -- and they don't even mention the dismal economy.


1. Shares may be more expensive than they're telling you. Wall Street says the market is still reasonably priced, at about 14 times forecast earnings. But two other measures tell a different story. The "Cyclically-Adjusted Price-to-Earnings Ratio" compares share prices to average earnings for the last ten years, not just for one year.

And a measure called "Tobin's q" compares share prices to the cost of replacing company assets. These may seem off-the-wall measures, but for more than a century they have proven very good guides for long-term investors. Right now both say the market is about 75% above its average value: Not a bubble, but expensive. These don't mean the market will tank. But they do suggest your long-term returns from here may be modest.

2. Bargains are hard to find. Value investors are gasping for air. Looking for stocks below, say, 16 times likely earnings, and with a dividend yield of more than 3%? Good luck. Once you weed out shares of companies on life support or those with meager interest cover, you're left with a smattering of decent-sized names - mostly drug companies and utilities, plus a handful of others such as Chevron and Kraft. In a market that's reasonably priced, you typically find lots of stocks on the bargain rack. Not here.

3. Is that really it? The stock market is now where it was before Lehman Brothers collapsed. And if you exclude financial stocks, the market value of U.S. equities is now within about 15% of the October, 2007, peak. To believe that (non-financial) stocks are reasonably valued today implies that they were pretty reasonable then, at the peak of the bubble - and that therefore most of the last three years was little more than a bad dream. Do you believe that? Do I?

4. The dividend yield is dismal. As the market has rallied, the yield has tumbled. Today it's just 1.7%, very low indeed by historic standards. David Rosenberg at Gluskin Sheff says the long-term average has been about 4.4%. Of course, dividends aren't the only way for investors to make money: Stock buybacks and growth can also generate returns. But dividends have historically been a key driver of investment profits, and the current level is paltry.

5. Corporate debts are far larger than people realize. Wall Street is selling a story that corporate balance sheets are in great shape and U.S. companies are simply awash with spare money. It's misleading. Some companies, naturally, are fine. But overall, corporate debts have been rising, not falling. Federal Reserve data show non-financial corporations owed $7.4 trillion at the end of the third quarter - an increase of $250 billion in a year, and a new record. As recently as 2005 the figure was just $5.5 trillion.

The Fed says nonfinancial corporations now have debts equal to 58% of their net worth - compared to just 41% five years ago. And when you add these debts to the value of equities, the so-called "enterprise value" of public companies is now about 2.2 times annual sales, according to FactSet. That's an extreme level - far higher than in 2006 or 2007, and exceeded only by the madness of 1999-2000.

Brett's #6 through #10 and worth the read!

Brett Arends writes ROI, or Return on Investment, offering analysis on what the latest news means for you and your money. The column covers investments, spending and broader personal-finance issues. Brett writes from a value-oriented and generally contrarian perspective. He has been writing about finance, in Europe and in the U.S., since the 1990s. Before that he worked as an analyst at McKinsey & Co., the strategy consultancy.


By: Brett Arends

Friday, December 24, 2010

TrimTabs Still Can't Figure Out Who Is Buying Stocks (Zero Hedge)

Great Post By  Zero Hedge
12-23-10
Save this post as we will all be reviewing
it several times throughout 2011

A year after Charles Biderman's provocative post first appeared on Zero Hedge, in which he asked just who is doing all the buying of stocks as the money was obviously not coming from retail investors (and came up with one very notable suggestion), today Maria Bartiromo invited the TrimTabs head once again (conveniently in CNBC's lowest rated show, during Christmas Eve eve, at a time when perhaps 5 people would be watching) in an interview which disclosed that after more than a year of searching, Biderman still has no idea who actually buying.

In response to Bartiromo's question if the retail investor, who left after the flash crash (thank you SEC), Biderman responds what every Zero Hedger has known for 33 weeks: "Retail investors are not coming back to the US. Those investors that are investing are buying global equities and are buying commodities. We are seeing lots money going into commodity ETF funds: gold, silver..." and the even more unpleasant summation: "individuals have been selling, companies are net selling, insider selling and new offerings are swamping any buyback and any cash M&A activity since QE 2 was announced. Pension funds and hedge funds don't really have that much cash to invest.

So what nobody's asking is what happens when QE 2 stops: if the only buyer is the Fed, and the Fed stops buying, I don't know what is going to happen...When I was on your show a year ago I was saying the same thing: we can't figure out who is doing the buying it has to be the government, and people said I was nuts. Now the government is admitting it is rigging the market." Cue Bartiromo jaw dropping.

As for the simple math of where the money is actually going:
"Money flows come out of income, take home pay of everybody plus money that came from real estate is down about $1 trillion a year. It peaked in the 3rd quarter of 2008, at $7 trillion, that's take home pay for everybody who pays taxes plus the money that came from real estate. It has now bottomed at $5.9 trillion. We are still down $1.1 trillion in money that people have to spend each year, that 16%. And some of the money that is leaving equity markets we think is going to pay bills."


Update: Charles has just sent in the following addendum
to his CNBC appearance:
Due to time constraints, what I didn’t get to address on CNBC today is what will happen after the Fed is either successful or not successful with QE2. The Fed is rigging the market by digitally creating money that is used to buy financial institutions assets — currently Treasuries, last year all kinds of toxic waste. What will happen when the Fed stops buying assets?

What the Fed is hoping is that QE2 actually works and the economy starts growing at 3+%. If that happens, unlikely as it is, then the Fed will end its QE activities. But for the stock market, if the only source of buying power, the Fed, withdraws its support, the market is likely to plunge to well below fair value. At that point perhaps some new source of money , i.e., China, et al will be able to buy US assets on the cheap.

The Fed is legally mandated to manage the economy, not the stock market. If the Fed’s QE is successful and the trickle down impact of higher equities creates a sustainable recovery, the Fed will gladly sacrifice the stock market to its legal mandate to manage the economy.

A more likely outcome is that while stocks will be higher by the end of QE2, economic growth will not be sustainable without government aid. That would then require additional QE. Stock prices could then keep rising for a while. At some unknowable now moment in time, unless the economy starts to grow again, no amount of QE can work forever in keeping the current stock market bubble from bursting.


Wednesday, December 22, 2010

Wednesday Withdrawal from U.S. Equity Market: Another $2.401 billion withdrawn while market manipulation continues

33rd consecutive week of U.S. Equity fund withdrawals. $89 billion withdrawn since 4/30/10. Stock Market continues its rise and other than a half dozen computers, no one else is trading nor does anyone give a rat's behind about the overall manipulation of what was once a market.

Washington, DC, December 22, 2010 - Total estimated outflows from long-term mutual funds were $8.48 billion for the week ended Wednesday, December 15, the Investment Company Institute reported today. Flow estimates are derived from data collected covering more than 95 percent of industry assets and are adjusted to represent industry totals.

Equity funds had estimated outflows of $161 million for the week, compared to estimated outflows of $901 million in the previous week. Domestic equity funds had estimated outflows of $2.40 billion, while estimated inflows to foreign equity funds were $2.24 billion. Current and historical data

Total Domestic Equity Flows/Week Ending
-$2.401 billion 12/15/10
-$2.673 billion 12/8/10
-$1.728 billion 12/1/10
-$2.594 billion 11/23/10
-$2.805 billion 11/17/10
-$660 million 11/10/10
-$1.132 billion 11/3/10
-$6.788 Billion for the month of October 2010
-$14.387 Billion for the month of September 2010
-$15.696 Billion for the month of August 2010
-$11.250 Billion for the month of July 2010
-$7.708 Billion for the month of June 2010
-$19.229 Billion for the month of May 2010

Since April 30th, 2010, $89.056 BILLION has been withdrawn from Domestic Equity Funds (This is the 33nd sequential weekly outflow from US stocks).

Charts via Zero Hedge


Wednesday, December 15, 2010

Wednesday Withdrawal from U.S. Equities Continues, 32nd consecutive week

This has simply gone beyond absurd. 32 weeks of withdrawals from the U.S. Equity giving further evidence that a handful of algo boys and girls play computer games between the opening and closing bell.

Washington, DC, December 15, 2010 - Total estimated outflows from long-term mutual funds were $3.25 billion for the week ended Wednesday, December 8, the Investment Company Institute reported today. Flow estimates are derived from data collected covering more than 95 percent of industry assets and are adjusted to represent industry totals.

Equity funds had estimated outflows of $1.40 billion for the week, compared to estimated inflows of $120 million in the previous week. Domestic equity funds had estimated outflows of $2.67 billion, while estimated inflows to foreign equity funds were $1.27 billion. Complete report and historical data

Total Domestic Equity Flows/Week Ending
-$2.673 billion 12/8/10
-$1.728 billion 12/1/10
-$2.594 billion 11/23/10
-$2.805 billion 11/17/10
-$660 million 11/10/10
-$1.132 billion 11/3/10
-$6.788 Billion for the month of October 2010
-$14.387 Billion for the month of September 2010
-$15.696 Billion for the month of August 2010
-$11.250 Billion for the month of July 2010
-$7.708 Billion for the month of June 2010
-$19.229 Billion for the month of May 2010

Since April 30th, 2010, $86.632 BILLION has been withdrawn from Domestic Equity Funds (This is the 32nd sequential weekly outflow from US stocks).


Charts via Zero Hedge